
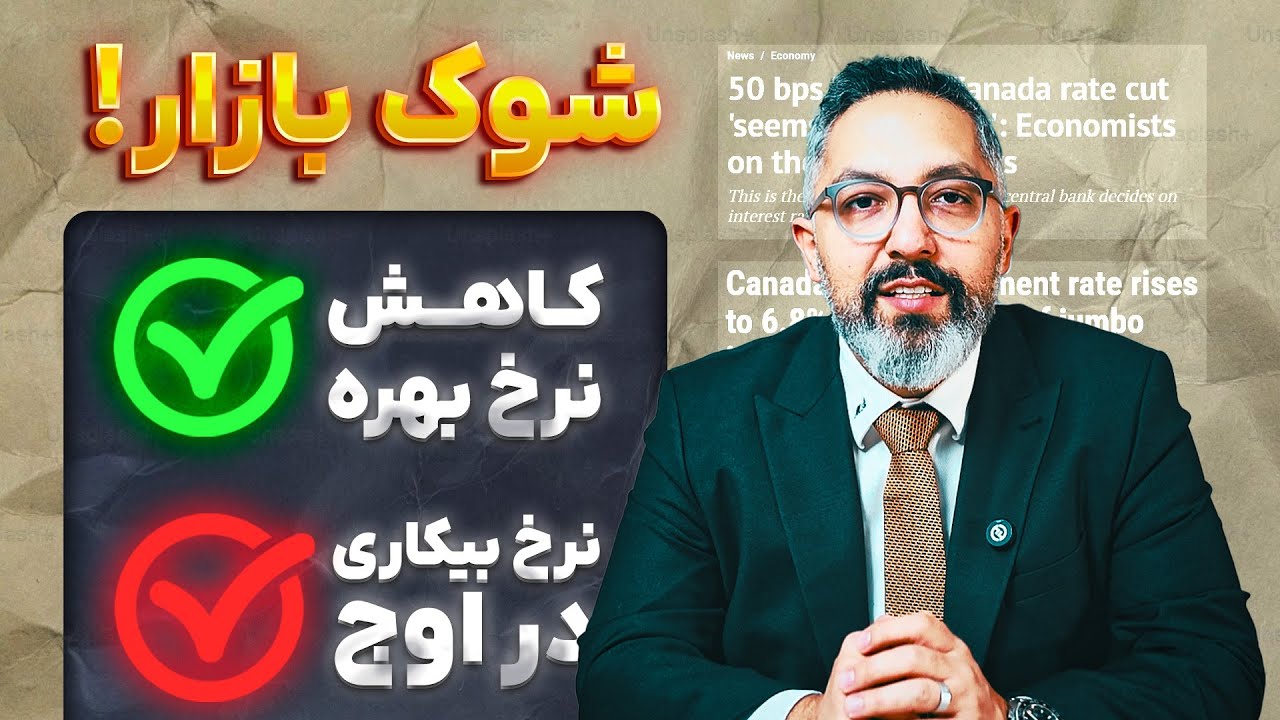
Based on Moe’s video of December 11, 2024. For this month’s numbers, see GTA Housing Market Today.
این مقاله به فارسیRead in FarsiOn Wednesday, December 11, 2024, the Bank of Canada cut its policy rate by half a percentage point, from 3.75% to 3.25%. It was the second half-point cut in a row, and the trigger was the labour market: unemployment had just been reported at 6.8%, the highest in eight years outside the pandemic period. Borrowing got cheaper that day.
I am Moe Asgarian, a broker with RE/MAX in Toronto, and I read these decisions the way my clients do, through the monthly payment on a mortgage rather than through the headline. In December 2024 the headline and the payment pointed the same way.
What the Bank of Canada Did on December 11, 2024
The policy rate moved from 3.75% to 3.25% on December 11, 2024. Half a point is a big single step, and this was the second one back to back. Going into that week, the expectation had been a quarter point, and the forecast only shifted in the final days. One more thing worth remembering about that period: the Bank of Canada was cutting much faster than the central bank in the United States, which is part of why Canadian and American rates looked so different at the end of 2024.
Why the November 2024 Jobs Numbers Forced a Half Point
The jobs report that landed on the Friday before the decision showed the unemployment rate at 6.8%, the highest in eight years apart from the pandemic years. That one number did the work. Economists who had been calling for a quarter point on December 11, 2024 moved to half a point once they saw it.
The odd part is that the count of new jobs added in November 2024 came in at double what had been expected. Both things were true at the same time: employers were hiring, and more people still could not find work. The wider picture in late 2024 was an economy that was not in good shape, and the rate decision reflected that rather than the one strong hiring figure.
Inflation Had Already Reached the 2% Target
Inflation is the other half of the story. One of the factors that shapes a Bank of Canada decision is where inflation sits, because once price growth is under control there is no reason to keep rates high. The target has been 2%, and as of the December 2024 decision that target had been reached. Some people worried at the time that cutting this quickly would bring inflation back later. That was a fair concern in December 2024, and it was the strongest argument against the speed of those cuts.

What Cheaper Money Did to the Canadian Dollar
Lower rates give markets a lift, housing included. They also put pressure on the Canadian dollar and push its value down further. That is the cost side of cheaper borrowing, and it was already visible in December 2024. With unemployment at 6.8%, though, there was not much choice in the short run. Getting the economy moving again and out of a slump mattered more at that moment than defending the currency.
The Tariff Risk Hanging Over 2025
Set all of that aside and one worry remained, on the other side of the border. Donald Trump was about to take office as president of the United States, and a great deal had already shifted around the world before he arrived. If he went ahead with 25% tariffs on imports of Canadian goods, the risk of a recession here was real, and the Bank of Canada would have to decide on that basis whether to keep cutting or to stop. As of December 2024, nobody knew which way that would break.

What the December 2024 Cut Meant for Toronto Buyers
Until the tariff question got answered, rates were coming down, and that made it a good window for anyone who wanted to take out a mortgage and enter the housing market at a lower rate. Every half point off the policy rate works its way into what a lender will charge and into what you pay each month, and that changes both your approval amount and your comfort level. In December 2024, that was the clearest reason to get your financing sorted and start looking rather than wait another quarter.
If you want to talk through what a rate picture like this means for your own purchase or sale in Toronto or the GTA, fill out the form at the bottom of this page or book a free consultation. Stay well and take care.

Frequently Asked Questions
How much did the Bank of Canada cut interest rates in December 2024?
On Wednesday, December 11, 2024, the Bank of Canada cut its policy rate by half a percentage point, from 3.75% to 3.25%. That was the second consecutive half-point cut.
Why did the Bank of Canada cut by half a point instead of a quarter?
The jobs report released on the Friday before the December 11, 2024 decision put the unemployment rate at 6.8%, the highest in eight years if you set aside the pandemic period. Forecasters who had expected a quarter-point cut changed to half a point after that number.
Was December 2024 a good time to take a mortgage in Toronto?
It was a cheaper time. With the policy rate down to 3.25% as of December 11, 2024, borrowing costs were falling and that helped buyers entering the Toronto market. The open question then was whether tariffs from the incoming US administration would stall the Canadian economy in 2025.